Payments strategy can become a discussion about rails, platforms, and digital assets before anyone has agreed which customer problem needs solving.
A corporate client may need a better cross-border experience. A treasury team may need more reliable visibility into cash. A business may need payments to arrive outside traditional processing hours. Each need creates a different case for change.
My starting point would be to define that need precisely. The choice of technology should follow from it.
Evaluate the full payment journey
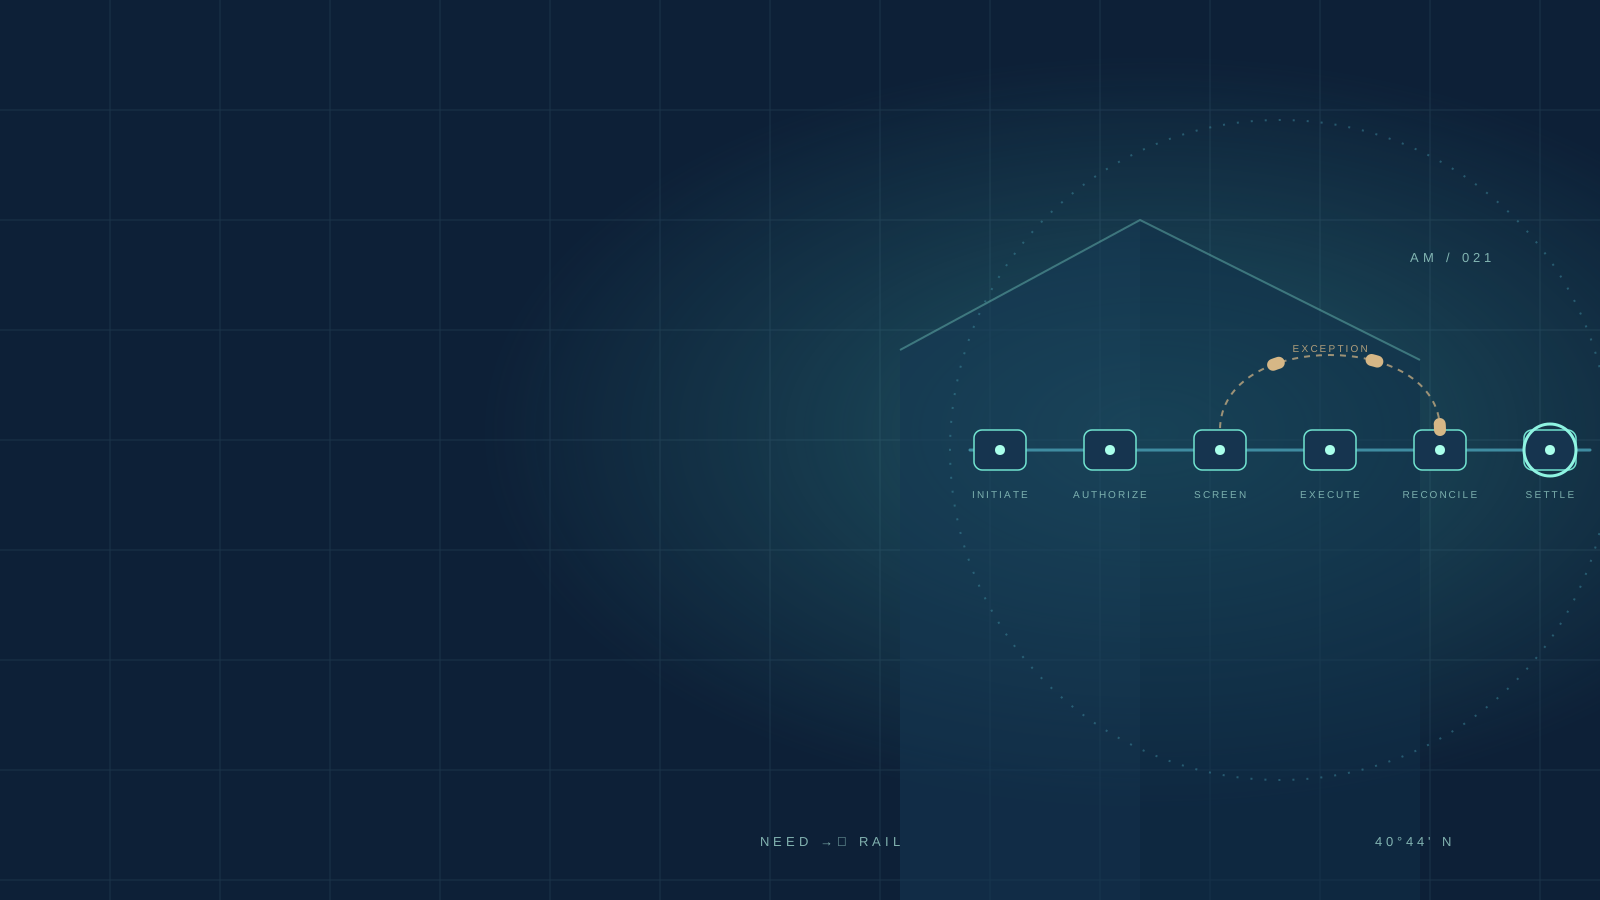
Our Enterprise Process Intelligence Framework, EPIF, examines the work from initiation through authorization, screening, execution, reconciliation, and exception handling. It establishes the current performance and what the customer actually needs to improve.
Sometimes the largest problem is outside the transfer itself. Incomplete instructions, manual approvals, poor status information, or reconciliation failures can create more friction than the underlying rail.
Removing those problems may deliver substantial value within the existing arrangement. In other cases, a new payment capability may be necessary. The evidence should determine the choice.
That principle applies to stablecoins and tokenized deposits as well. They should be evaluated against a specific use case and the available alternatives, with careful attention to their different structures and risks.
Choose the role and design the operation
An institution considering digital-asset payments needs to decide where it intends to participate. Issuing, providing custody, processing transactions, and distributing a partner’s service involve different capabilities, dependencies, and obligations.
EPIF structures the operating and investment decisions. Legal, compliance, treasury, security, and risk specialists need to assess the applicable requirements and proposed arrangement.
The design must address customer eligibility, financial-crime controls, liquidity, reconciliation, access, third-party dependencies, and incident response. Redemption arrangements and the treatment of customer claims need particular attention where relevant.
Operating hours matter too. A service available around the clock needs a credible approach to funding, monitoring, customer support, and recovery during those hours. The staffing and control costs belong in the business case.
Test a complete service
A bounded pilot should include more than a successful transaction. Test rejected instructions, duplicate submissions, unavailable dependencies, funding shortfalls, and the handling of incorrect payments under the arrangement’s rules. Establish who makes decisions when normal processing fails.
Measure adoption, completion rates, repair effort, reconciliation quality, customer experience, and total cost per successful payment. Include any effects on deposits, liquidity, existing revenues, and ongoing support costs that are relevant to the institution.
EPIF’s Sustain stage asks whether those results hold as usage grows. A pilot may depend on manual support that becomes expensive at scale. That work needs to be visible before the institution makes a larger commitment.
Payments modernization earns its place when customers receive a better service and the institution can operate it reliably at acceptable economics. That is the case worth taking to an investment committee.
Where to start
Use EPIF to compare payment options against one defined customer need, including the operating model and cost required to deliver it.
Related
Fintech and payments
Documented result: 60%+ of orders from new customers
Know Your Agent: when the customer sends software